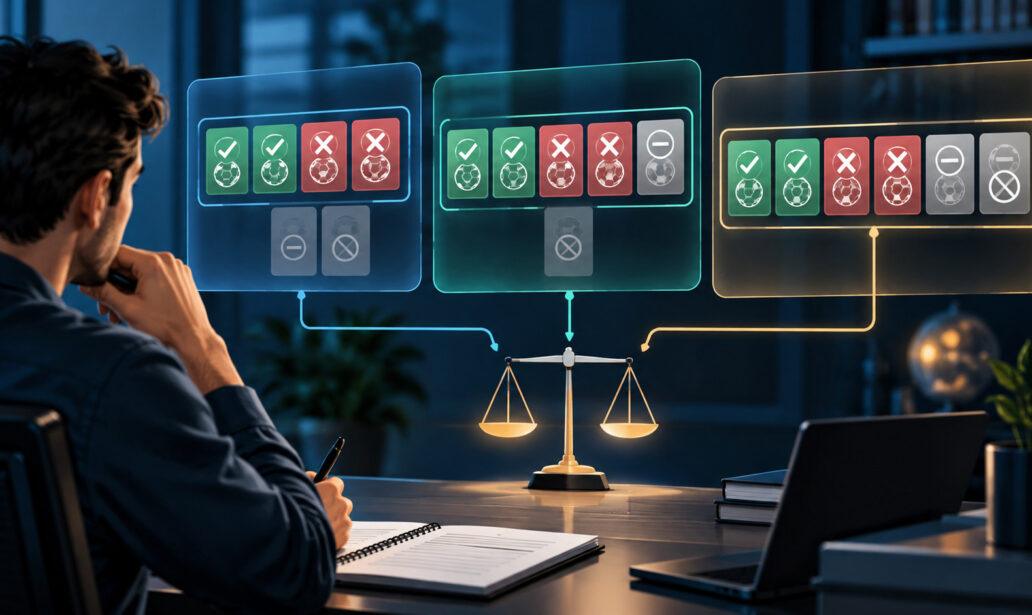
Two betting performance reports can use the same results, show the same financial loss and still calculate different return-on-investment (ROI) percentages. The difference may come down to how each report handles pushed, voided and refunded wagers.
This creates a problem for anyone evaluating betting analytics. A dashboard can display an accurate profit figure while calculating its ROI using a denominator that is different from another platform’s.
The number of bets recorded, the amount originally staked and the amount included in an ROI calculation are not always identical.
Understanding these differences matters when comparing prediction services, reviewing historical model results or checking whether a published performance record reflects actual settled transactions.
One Betting Record, Three Different ROI Figures
Consider a completely hypothetical record containing six wagers, each with an original stake of $25.
Four wagers receive ordinary win-or-loss settlements. One pushes, meaning the original stake is returned without profit or loss. Another is voided, and its stake is also fully refunded.
The settled results are:
- Two winning wagers at decimal odds of 1.80, each producing $20 in net profit.
- Two losing wagers, each producing a $25 loss.
- One pushed wager returning its $25 stake.
- One fully voided wager returning its $25 stake.
The two wins produce $40 in profit. The two losses cost $50.
Total net result: −$10.
Nothing about that result changes when the record is analyzed using different denominator conventions.
However, the reported return percentage can change.
| Reporting convention | Stake included | Net result | Reported return |
|---|---|---|---|
| Won and lost wagers only | $100 | −$10 | −10.00% |
| Won, lost and pushed wagers | $125 | −$10 | −8.00% |
| All original stakes, including voided wagers | $150 | −$10 | −6.67% |
All three calculations use the same basic formula:
Return percentage = Net profit or loss ÷ Included stake × 100
The difference comes entirely from the denominator.
This does not mean all three conventions are equally suitable for every purpose.
The first measures returns on wagers resolved as wins or losses. The second also counts stakes tied up in pushed wagers. The third measures the result against every original stake recorded, including money subsequently refunded because the wager was voided.
The third figure is better understood as a gross-stake reporting measure than as a pure return on stakes exposed to a resolved outcome.
Each calculation can describe its stated sample accurately. But comparing percentages calculated under different conventions can be misleading.
This is why published betting returns should always identify which transactions enter the numerator and denominator.
A Push and a Voided Bet Can Have the Same Cash Result but Different Meanings
A push commonly occurs when a wager’s stated condition ends exactly on the quoted line.
For example, a hypothetical total-points wager on over 44 points may push if the event finishes with exactly 44 points, assuming ordinary whole-number total settlement rules.
The original stake is returned, producing no net profit or loss.
A voided wager is different.
It may be canceled because a sporting event is postponed, an eligible participant does not take part, the market cannot be settled under applicable rules or another recognized cancellation condition occurs.
In both situations, a fully refunded single wager produces a zero net financial result.
However, the reason for settlement matters when interpreting model performance.
A push occurs because of a possible outcome within the market’s settlement structure. A void may occur because the wager was no longer valid or eligible for ordinary settlement.
These distinctions are visible in FanDuel’s Colorado sportsbook house rules, effective September 30, 2026. The rules address player participation, canceled events, settlement changes and the treatment of voided selections within parlays. They also specify that individual sport rules can override general rules. FanDuel
For analysts, the important question is not simply whether the stake was refunded.
It is why the wager was refunded and whether the corresponding prediction should remain in a particular performance sample.
Suppose a player-prop forecasting model issues 100 predictions, but 15 are later voided because relevant players did not participate.
If the analyst evaluates only the 85 settled outcomes, the report should explain that exclusion.
It should also show whether the model’s underlying forecasts were designed to account for nonparticipation.
Otherwise, the analyst may be evaluating a different selection of events from the one the model originally forecast.
This does not automatically invalidate the analysis. It means the evaluation population must be defined clearly.
Settlement Rules Are Part of the Data, Not Just the Fine Print
Sportsbook settlement conditions are not universal.
They can vary by operator, sport, market and jurisdiction.
Massachusetts provides one useful example.
The state’s regulation on canceled or voided sports wagers, 205 CMR 238.35, describes circumstances in which wagers may be canceled, the required treatment of refunds and the need to maintain cancellation records. Legal Information Institute
Among the circumstances addressed are certain event cancellations, participant nonparticipation and changes affecting an event’s agreed conditions.
The regulation also establishes procedures for cancellations requiring regulatory authorization.
This matters when reviewing betting analytics because the settlement result cannot always be inferred from the final sports score.
A historical database containing only event outcomes and quoted odds may therefore lack enough information to reproduce the actual financial result.
An analyst should distinguish at least four separate records: the original prediction, the accepted wager, the event outcome and the final sportsbook settlement.
A prediction may be statistically correct while its associated wager is voided.
Likewise, a prediction may describe the final sporting outcome accurately but have no relationship to the final financial result if the market settled under different conditions.
For a valid return calculation, the sportsbook’s applicable settlement record must take priority over a simple prediction label.
Parlays and Cash-Outs Make the Accounting More Complicated
Ordinary win-or-loss accounting becomes less straightforward when wagers contain multiple selections.
A parlay combines several outcomes into one ticket.
If one selection is voided, the entire ticket does not necessarily become void.
Under the Colorado FanDuel rules cited above, remaining parlay selections can continue, with the overall price recalculated according to the applicable rules.
That means an analyst cannot automatically grade a three-selection parlay as canceled simply because one selection was voided.
The full ticket’s actual settlement must be reconstructed.
There is also a double-counting risk.
Suppose someone places a hypothetical $30 three-selection parlay.
The original financial stake is $30, not $90.
An analytical database may preserve three individual selection records, but those records must remain linked to the original ticket.
Counting the full $30 stake three times would overstate the total amount risked.
The reverse problem occurs if a reporting system treats each selection as a separate successful prediction while presenting only the combined ticket’s financial return.
Prediction-level accuracy and ticket-level financial performance are different measurements.
Cash-Out Transactions Need Their Own Treatment
A cash-out is another source of reporting errors.
Suppose a hypothetical $50 wager is fully cashed out for $35, with no additional fee.
The financial result is:
$35 returned − $50 staked = −$15
The wager generated a $15 loss.
It should not be recorded as a winning wager merely because money was returned.
Nor should it automatically be treated as a push.
A partial cash-out is more complicated because one portion of the original exposure may be settled while another remains open.
An analyst must preserve the amount closed, the amount returned and the remaining outstanding stake.
Combining these transactions into a single win-or-loss label can hide the actual financial result.
If a sportsbook subsequently corrects a settlement, the record should also preserve the original settlement and later adjustment rather than silently overwriting the history.
How to Build a Consistent Betting ROI Report
A useful ROI report begins with a clearly defined accounting policy.
The analyst should identify the reporting period, types of transactions included and treatment of refunded stakes before calculating performance.
The WagerProof guide to sports betting ROI and performance records provides a documented example of one reporting convention. Its review worksheet includes pushed stakes in the denominator, excludes fully voided wagers and treats cash-outs separately. It also acknowledges that other trackers use different conventions. WagerProof
That is an important qualification.
There is no benefit in treating a particular denominator convention as universally correct when the stated measurement purpose differs.
For example, a model evaluator might calculate returns using only wagers that received ordinary win-or-loss settlements.
An operations analyst might separately measure total originally accepted stakes, refunded amounts and final settled exposure.
Both can be useful.
The problem arises when those different measurements are given the same label without explanation.
For an auditable record, preserve the original accepted stake and odds alongside the settlement status, actual returned amount, net profit or loss, and any subsequent adjustments.
A separate field should indicate whether each transaction contributes to the selected ROI calculation.
BettorSearch’s existing guide to building and managing a betting database discusses data relationships, transaction integrity and audit trails. Those database principles are directly relevant to maintaining distinct original and final settlement records.
The analyst can then calculate returns consistently without deleting transactions simply because they did not produce a win or loss.
One particularly useful safeguard is to publish the underlying totals beside the percentage.
A report showing −8% ROI should also disclose the net loss, included stake, number of ordinary settlements, pushes, voids and unresolved transactions.
Without those details, the percentage is difficult to reproduce.
Why Sportsbook Revenue Hold Is Not the Same as Personal ROI
A separate source of confusion appears when individual betting performance is compared with official sportsbook revenue statistics.
Regulators report operator-level financial results using accounting and reporting definitions that differ from an individual model’s ROI calculation.
For example, the Massachusetts Gaming Commission’s sports wagering revenue reports publish operator-level revenue information and explain that previously reported figures may subsequently be updated. The page listed August 2026 reports in its September 21, 2026 update. Massachusetts Gaming Commission
These reports serve regulatory and industry-analysis purposes.
They do not measure whether an individual forecasting model has a statistical advantage.
Sportsbook handle generally refers to wagering volume under the applicable reporting definition. Realized operator hold relates wagering revenue to the relevant betting volume.
Neither is interchangeable with the return achieved by one bettor, one forecasting model or a selected portfolio of wagers.
The accounting base also matters when comparing sports-event contracts traded on prediction markets with traditional sportsbook activity.
Contract trading volume is not automatically equivalent to sportsbook handle, and an event-contract trading fee is not identical to a sportsbook’s quoted margin.
An analyst should identify what each source actually measures before combining the figures.
The Strongest Report Is the One Another Analyst Can Reproduce
The hypothetical six-wager example produced the same $10 loss under every reporting convention.
Only the denominator changed.
That difference was enough to move the displayed return from −10% to −6.67%.
The underlying financial outcome did not improve.
This is why an impressive betting ROI should never be interpreted without the transaction definitions behind it.
The same caution applies to model comparisons, prediction-service rankings and historical backtests.
A credible performance report should explain how pushes, voids, partially settled tickets, cash-outs and unresolved wagers affect its totals.
It should also preserve original transactions so another analyst can reproduce the calculation.
A clean accounting record cannot demonstrate that a betting strategy will generate future profits. Historical performance remains uncertain, and gambling should not be treated as reliable income.
But consistent settlement accounting can establish something fundamental: whether the reported percentage accurately describes the transactions it claims to measure.